
Pillar 3a for Expats in Switzerland: 2026 Deadline, 2027 Limits, and What Happens When You Leave
Pillar 3a is the Swiss tax-deductible retirement account. Foreigners can use it like anyone else, but three points are specific to expats: the deduction when you pay tax at source, catch-up payments for missed years, and the withdrawal when you leave.
Published 16 November 2026 · Reviewed & updated 16 November 2026 · By bergmoney Research
Anyone with AHV-liable earned income in Switzerland can pay into pillar 3a, whatever their nationality or permit. The limit is CHF 7,258 for 2026 and CHF 7,373 for 2027 if you have a pension fund. The 2026 payment must be on the 3a account by 31 December 2026. If you pay tax at source, you get the deduction only on request, by 31 March 2027. When you leave Switzerland for good you can withdraw the full balance.
Affiliate disclosure: some links on this page (Alpian, Yapeal) are affiliate links. If you open an account through them we may receive a referral reward at no extra cost to you. Our editorial position is not influenced by referral rewards. This page is general information, not tax or investment advice. Read how we make money.
What pillar 3a is and who can use it
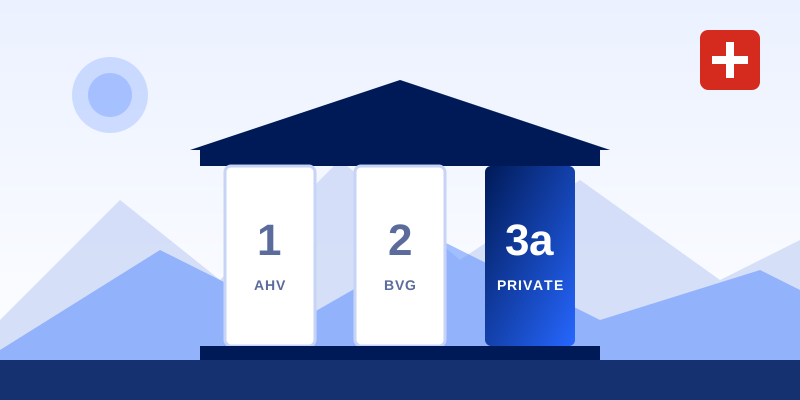
The Swiss pension system has three pillars. The first is the state pension (AHV), the second is the pension fund from your employer (BVG), and the third is private saving. Pillar 3a, called Säule 3a in German, is the tied part of the third pillar: the money is locked until retirement, and in return you deduct your contributions from taxable income.
You qualify if you have earned income in Switzerland that is subject to AHV contributions. Nationality and permit type (B, C, L, G or S) play no role. Without earned income, for example as a non-working spouse, you cannot pay in.
You can withdraw from age 60, five years before the AHV reference age. Earlier withdrawals are allowed for buying a home you live in, for starting self-employment, in case of disability, and when you leave Switzerland for good.
Limits for 2026 and 2027
| Your situation | 2026 | 2027 |
|---|---|---|
| Employed, member of a pension fund | CHF 7,258 | CHF 7,373 |
| Earned income without a pension fund (many self-employed) | 20% of net earned income, max CHF 36,288 | 20% of net earned income, max CHF 36,864 |
Source for 2027: Federal Council media release of 2 October 2026 (in German). The new amounts apply from 1 January 2027.
What the deduction is worth
The saving depends on your canton, commune and income. As an illustration only: at a marginal tax rate of 25%, a contribution of CHF 7,258 lowers your tax bill by about CHF 1,815. Your own rate may be lower or higher.
The 2026 deadline
A contribution counts for 2026 only if it is credited to your 3a account by 31 December 2026. The date you send the transfer does not count.
Banks and 3a apps publish their own cut-off dates, usually a few working days before the end of the year. Opening a new 3a account also takes time, because the provider has to identify you first.
Practical rule: open the account in the first half of December and send the payment by mid-December. If you already have a 3a, a monthly standing order removes the year-end rush.
Catch-up payments for missed years
Since 1 January 2025 the law allows you to pay in later for years in which you contributed nothing or less than the maximum. 2026 is the first year in which this is possible, for the gap from 2025.
- Only gaps from the 2025 contribution year onwards count. Earlier years are excluded for good.
- You can go back up to ten years.
- You must have had AHV-liable earned income in Switzerland in the gap year and in the year you pay.
- You must first pay the full ordinary contribution for the current year.
- The extra payment per year is capped at the limit for people with a pension fund (CHF 7,258 in 2026).
- A gap year is closed with one payment. You cannot spread it over several years.
- It is not possible once you have started drawing 3a retirement benefits.
Example. You moved to Switzerland in 2025, earned a Swiss salary with a pension fund and paid nothing into 3a that year. In 2026, you can pay CHF 7,258 for 2026 and a further CHF 7,258 for 2025, and deduct both in your 2026 tax year.
If you arrived in 2026, there is no gap to fill yet: you had no Swiss income in 2025. The request goes to your 3a foundation in writing, and each provider has its own form, so ask before you transfer the money.
Tax at source: how to get the deduction
Most foreigners without a C permit have tax deducted from their salary each month (Quellensteuer). That tariff does not know about your 3a payments. How you get the deduction depends on your situation.
- Resident, taxed at source, gross salary under CHF 120,000You request a subsequent ordinary assessment (nachträgliche ordentliche Veranlagung) from your cantonal tax office by 31 March of the following year. For 2026 contributions that is 31 March 2027. Cantons such as Zurich state that this deadline cannot be extended.
- Resident, gross salary of CHF 120,000 or moreYou are assessed in the ordinary way in any case and enter the 3a contribution in your tax return.
- C permit, or married to a Swiss citizen or C-permit holderYou file a normal tax return and claim the deduction there.
- Cross-border commuter (permit G)A Swiss deduction is available only if you count as quasi-resident, which generally means that at least 90% of your household's worldwide income is taxable in Switzerland. Without that status a 3a rarely pays off.
Check before you switch. For residents, the request generally stays in force for the following years. An ordinary assessment uses the tax rate of your commune, which can be higher than the source-tax tariff, and it also covers your worldwide income and assets. Ask your cantonal tax office or a tax adviser to estimate the result first.
Leaving Switzerland
When you leave for good you have two options.
- Withdraw the full balancePillar 3a can be paid out in full on a final departure, to any country. This differs from the pension fund, where the mandatory part usually stays in Switzerland if you move to an EU or EFTA state. The foundation asks for your deregistration confirmation and proof of your address abroad.
- Leave it investedThe account can stay until retirement age. You cannot add to it once your Swiss earned income ends.
How the withdrawal is taxed
A lump-sum withdrawal is taxed once, at a reduced rate and separately from other income. Where you live on the payment date decides who taxes it.
- Paid out while you still live in Switzerland: your canton of residence taxes it.
- Paid out after you have left: a withholding tax applies in the canton where the 3a foundation has its seat. The rates differ between cantons.
- Your new country: it may tax the payment as well, or a double-taxation agreement may let you reclaim the Swiss withholding tax. This depends on the country.
Two more points for the planning. Check the provider's fee for a withdrawal on departure. And if you are a US citizen or green-card holder, ask a tax adviser before investing in 3a funds, because US tax rules treat Swiss funds unfavourably and some providers do not accept US persons.
Choosing a provider
A 3a account is held by a pension foundation. You reach it through a bank, an insurer or a 3a app. Five things matter for expats.
All-in cost
Add the management fee and the cost of the funds inside. A difference of 0.3% a year adds up over twenty years.
Bank or app, not insurance
If you may leave Switzerland, avoid 3a insurance policies. They run for decades and cancelling early usually costs money.
Where the foundation sits
The canton of the foundation's seat decides the withholding tax on a withdrawal after you have left.
Fee for leaving
Some providers charge for a withdrawal on departure abroad. Read the fee schedule before you open.
Language
App and documents in English, if you need them.
Alpian pillar 3a
Alpian is a Swiss bank with a FINMA banking licence, and it offers a 3a inside its app. According to Alpian's own product page:
- management fee of 0.60% a year, plus fund costs of around 0.15% and VAT;
- invested fully in BlackRock funds, with nine strategies (Swiss, Global, or Global with a 5% Bitcoin allocation);
- minimum first deposit of CHF 300;
- the pension foundation behind it is lemania-pension (FRPI);
- opened and managed in the Alpian app, which is available in English.
Alpian also advertises a reimbursement of management and foundation fees for 2025 and 2026, limited to the first 1,000 accounts. Check in the app whether it still applies. Its fact sheet lists extra fees for a home ownership withdrawal and for a final departure abroad, so read it if you expect to leave.
Alpian fits if you want your bank account and 3a in one English-language app. On price alone, specialised 3a apps such as VIAC, finpension or frankly are usually cheaper, so compare the all-in cost. For the bank itself, see our Alpian review.
Open Alpian →Affiliate link. The code PCNC86 relates to the bank account bonus, not to the 3a. Terms can change.
The account you pay from
Contributions go by bank transfer to the foundation's Swiss account. The simplest source is a Swiss account in your own name, the one your salary lands on, with a monthly standing order.
Yapeal does not offer a pillar 3a. It is relevant here only as that Swiss account: a CH IBAN for salary, standing orders and QR-bills, from which you can fund a 3a held elsewhere. Details in our Yapeal review.
No Swiss account yet? Start with our guide to opening a Swiss bank account as a foreigner or the best bank for foreigners in Switzerland comparison.
Mistakes to avoid
Paying on 30 December
A transfer that arrives in January counts for the next year, and the 2026 allowance is lost unless you later use a catch-up payment.
Paying in while taxed at source and never filing the request
Without the request by 31 March, the deduction is gone for that year.
Signing a 3a insurance policy in your first months
Easy to sign, expensive to leave if your plans change.
Overpaying
Amounts above the limit are not deductible and have to be paid back by the foundation.
Withdrawing before you deregister, without checking the tax
The tax differs between a withdrawal as a resident and one after departure. Compare both before you choose the date.
Frequently asked questions
Can foreigners open a pillar 3a in Switzerland?+
Yes. Nationality and permit type do not matter. What counts is earned income in Switzerland that is subject to AHV contributions. Employees and the self-employed with such income can pay in.
What is the maximum pillar 3a contribution in 2026?+
CHF 7,258 if you belong to a pension fund. Without a pension fund, 20% of your net earned income, up to CHF 36,288.
What is the maximum pillar 3a contribution in 2027?+
CHF 7,373 with a pension fund and up to CHF 36,864 without one. The Federal Council set the new amounts on 2 October 2026 and they apply from 1 January 2027.
What is the deadline for 2026 contributions?+
The money must be credited to your 3a account by 31 December 2026. Providers set their own cut-off a few days earlier, so pay in by mid-December to be safe.
Can I pay for years I missed?+
Only for gaps from 2025 onwards, and only up to ten years back. You must first pay the full contribution for the current year, and you must have had AHV-liable income in Switzerland in the year you are catching up on. Years before 2025 cannot be made up.
I pay tax at source. Do I get the 3a deduction automatically?+
No. The source-tax tariff does not include 3a contributions. To get the deduction you request a subsequent ordinary assessment from your cantonal tax office by 31 March of the following year.
What happens to my pillar 3a if I leave Switzerland?+
You can withdraw it in full when you leave for good, whatever the destination country, or leave it invested until retirement age. A withdrawal after departure is taxed at source in the canton where your 3a foundation has its seat.
Can I keep paying into pillar 3a after I leave?+
No. Once you no longer have AHV-liable earned income in Switzerland, you cannot contribute. Existing savings can stay invested.
Does Yapeal offer a pillar 3a?+
No. Yapeal offers accounts and cards. For 3a you need a pension foundation, which you reach through a bank or a 3a app such as Alpian, VIAC, finpension or frankly.
Is a pillar 3a worth it if I stay only two or three years?+
Often yes, if you can claim the tax deduction, because you get the tax saving each year and can withdraw the money when you leave. Check the withdrawal fee of your provider and the tax in your next country first. This is general information, not tax advice.
Should I choose a bank or an insurance 3a?+
If you may leave Switzerland, a bank or app-based 3a is the flexible choice: you can stop paying at any time without loss. Insurance policies run for decades and usually lose value if you cancel early.
Summary
Pillar 3a is open to every expat with a Swiss salary. For 2026 you can pay in up to CHF 7,258 with a pension fund, and the money has to arrive by 31 December. From 2027 the limit is CHF 7,373. If you missed 2025, you can make it up in 2026 on top of the regular amount.
If you pay tax at source, file the request for an ordinary assessment by 31 March 2027, or the deduction is lost. If you may leave Switzerland, pick a bank or app-based 3a, and check the departure fee and the foundation's canton before you open.
Next steps
Affiliate links · no extra cost to you · disclosure
Published 16 November 2026 · Reviewed & updated 16 November 2026 by bergmoney Research.
Spotted an outdated detail or a changed limit? Tell us. We update our guides regularly.